The short answer
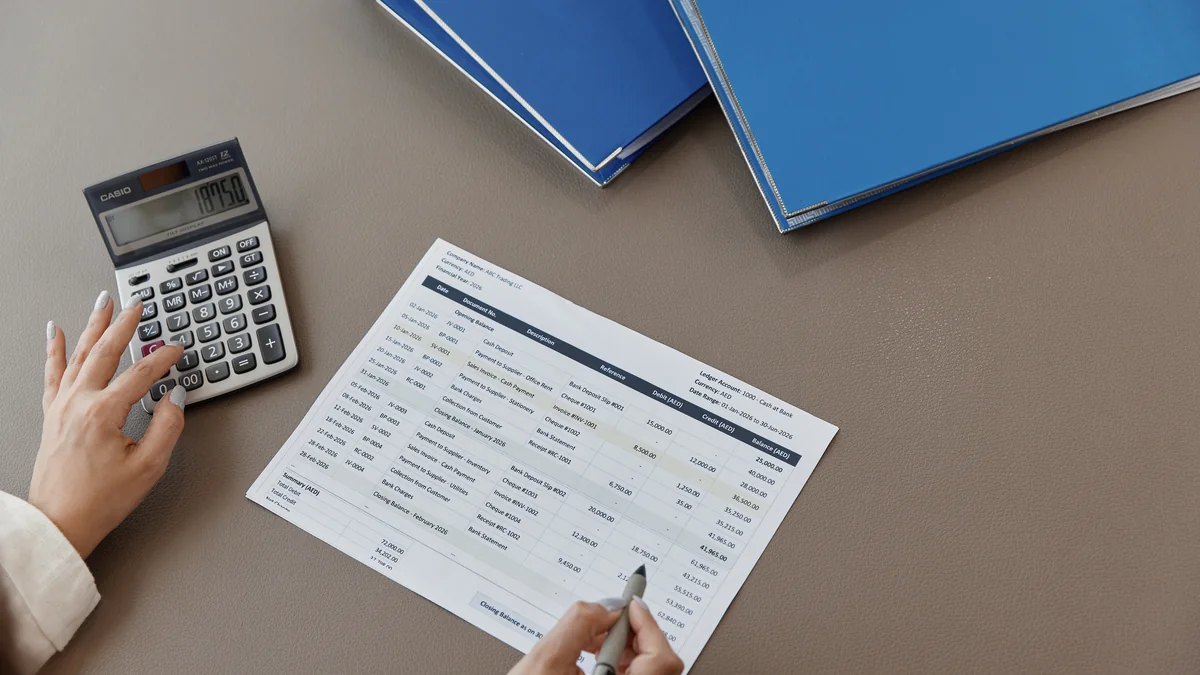
Start the books when the company starts spending, not when it becomes profitable. Keep business records organised, distinguish owner funding from sales and reconcile the bank regularly. A simple monthly close should tell you what was earned, what is owed and which documents are still missing.
Create one record trail for every transaction
For each sale, retain the agreed scope, invoice and evidence of collection. For each purchase, keep the supplier invoice, payment evidence and business purpose. A bank entry tells you money moved; it may not tell you what was purchased, who owes the company money or whether an invoice has the necessary information.
Create a secure folder structure and a naming rule that staff can follow. Keep originals and make them searchable by supplier/customer and date. Limit access to payroll and identity records separately from general purchase paperwork.
Separate owner money from revenue
Record shareholder funding and money paid personally on behalf of the company separately from customer sales. Ask the accountant how to classify and document loans, capital contributions and reimbursements. Do not make that distinction disappear by posting every receipt as income.
Likewise, do not record an unpaid customer invoice as collected just because the business made a sale. Review outstanding receivables and supplier balances alongside the bank balance. The company can look profitable while being short of cash.
What should the monthly close include?
Scroll sideways to see every column.
| Check | What it catches |
|---|---|
| Bank reconciliation | Missing entries, duplication and unexplained transfers |
| Unpaid sales invoices | Overdue collections and disputes |
| Supplier balances | Bills that still need paying |
| Expense evidence | Missing invoices and unclear business purpose |
| Payroll reconciliation | Differences between approved pay and recorded payments |
| Tax review flags | Transactions the tax adviser needs to assess |
Keep accounting and tax connected
Ask the tax specialist what evidence the records need to support, including uncertain VAT treatment or transactions with related parties. The FTA stresses retaining relevant Corporate Tax records for at least seven years after the relevant period. [1] Other record categories may have different requirements; set retention with the relevant adviser.
A monthly process does not replace specialist judgement, but it makes that judgement possible before a filing deadline. Share a short exceptions list—missing invoices, unclear transfers and unreconciled balances—rather than sending a large folder with no explanation.
Define the accountant’s deliverables
- A monthly close timetable with a deadline for staff to send documents.
- Bank reconciliation and an agreed set of financial reports.
- An outstanding-invoice and supplier-balance review.
- A missing-evidence list with named owners.
- A clear handoff to payroll and tax specialists, including who approves submissions.
Questions worth answering
Do I need records before the first sale?
Yes. Formation expenditure, deposits and owner funding create transactions that need to be explained and recorded.
Is outsourcing accounting the same as appointing an auditor?
No. Bookkeeping and audit preparation are distinct from an independent audit engagement. Confirm the scope and any audit requirements separately.
Official sources
Source pages checked 10 October 2026. Numbered references in the guide correspond to the sources below.
Your next step
Choose the support that fits this decision. Each link takes you to the relevant service page.
This guide is practical preparation, with official sources where relevant. Company-specific requirements need an assessment of your circumstances. How these guides are prepared.